Florida first-time home buyer programs help with down payments and closing costs. Most programs run through Florida Housing Finance Corporation and approved lenders. This guide explains each option, the rules, and the steps to apply in Tampa Bay.
Who Counts as a First-Time Buyer in Florida?
The Three-Year Rule
Most programs define a first-time buyer as someone with no ownership interest in a primary residence in the past three years. You may qualify even if you owned a home long ago. Check each program’s rules before you apply.
Veteran Exceptions
Some programs relax the rule for veterans. A valid DD-214 can satisfy the first-time buyer test under certain programs. Ask your lender how that applies to you.
Florida Housing Finance Corporation Programs
Who Runs the Programs
Florida Housing Finance Corporation runs the state’s main first-time buyer programs. It works with approved lenders across the state. Its loans are 30-year fixed-rate mortgages.
Florida Hometown Heroes
Hometown Heroes offers up to $35,000 in down payment and closing cost help. It serves eligible workers such as health care staff, school employees, first responders, childcare workers, and military members. The program reopened on July 13, 2026 with $50 million in funding.
Florida Assist and Florida HLP
Florida Assist is another down payment assistance loan for eligible buyers. The Florida HLP second mortgage offers $10,000 at 3 percent over 15 years. Both programs have income and credit rules.
How Much Help Can You Get?
Florida first-time buyers can often find $10,000 to $35,000 or more in help. Many programs use repayable second mortgages. Some balances come due when you sell, refinance, or move out.
Local and County Programs
County and city programs can add more help. Funding varies by area and year. Ask your lender about current Hillsborough County options.
Work With a Housing Counselor
A HUD-approved housing counselor can review your budget at low or no cost. Counselors explain each program in plain language. Ask your lender for a referral.
Federal Loan Options
FHA Loans
FHA loans can require as little as 3.5 percent down with a 580 credit score. Mortgage insurance applies to these loans. Compare the total cost before you choose.
VA Loans
VA loans offer zero down payment to eligible veterans and active-duty members. The VA home loan program sets the eligibility rules. Our guide on using a VA loan for a second home covers repeat use.
USDA Loans
USDA loans offer zero down payment in eligible rural areas. Some areas near Tampa Bay may qualify. Check the USDA map before you rule it out.
Program Requirements to Expect
Income and Price Limits
Programs set income limits and purchase price limits by county. Limits change each year. Ask your lender for the current Hillsborough County numbers.
Credit Score and Debt
Lenders set minimum credit scores and debt-to-income ratios. Requirements vary by program and lender. Pay down card balances before you apply.
Homebuyer Education
Many programs require a homebuyer education course. The course covers budgeting and mortgage basics. Finish it early so your closing stays on schedule.
How to Apply Step by Step
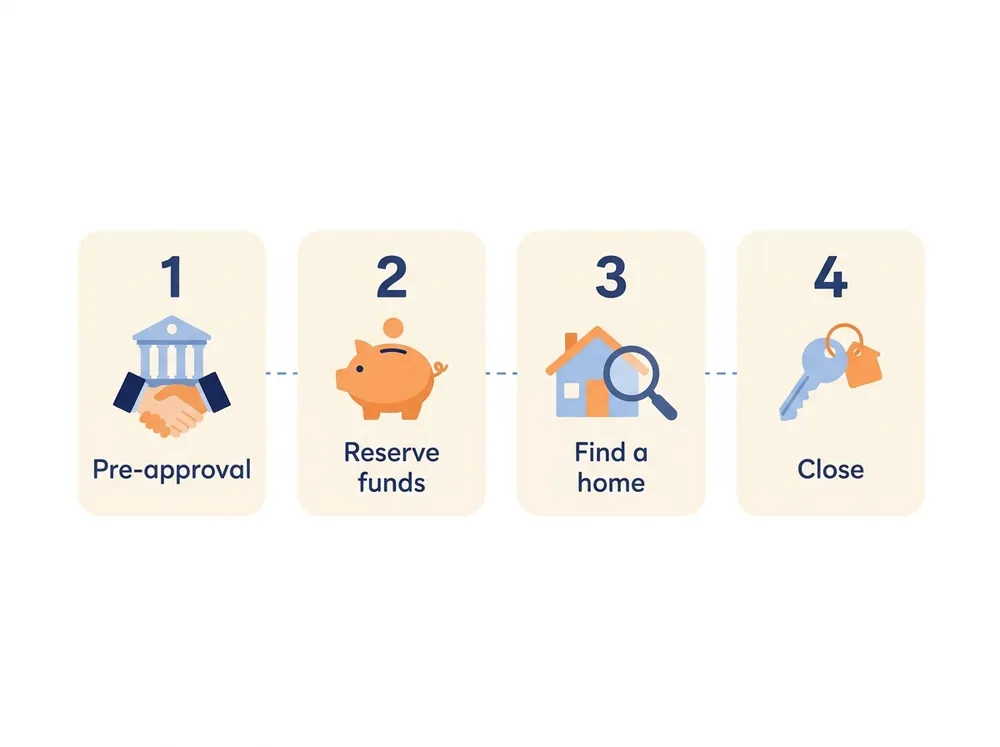
Step 1: Get Pre-Approved
Choose a lender approved for Florida Housing programs. Share your income, debts, and savings. Read our guide on deciding to buy while you wait.
Step 2: Reserve Your Funds
Funds for some programs run first come, first served. Florida Housing committed all 2025-2026 Hometown Heroes funding in six months. Reserve your funds as soon as you have a contract.
Step 3: Find Your Home
Search within your program’s price limit. Browse new homes in Riverview under $300K for a starting point. Compare loan types in what is the best type of home loan.
Choose an Agent Who Knows the Programs
Pick an agent who has worked with assistance programs. They know the timelines and lender needs. Ask about their recent closings.
Step 4: Close and Move In
Your lender coordinates the funds at closing. Keep your documents ready. File for the Florida homestead exemption after you move in.
Costs Beyond the Down Payment
Closing Costs
Closing costs include lender fees, title charges, and prepaid items. Down payment assistance can cover some of them. Ask for a written estimate early.
Set a Monthly Budget
Choose a monthly payment you can afford with taxes and insurance included. Add a cushion for repairs. Stay below the amount your lender approves.
Taxes and Insurance
Property taxes and insurance add to your monthly payment. Compare the full cost with our renting vs buying in Tampa guide. Ask your lender to include escrow in every estimate.
Mistakes First-Time Buyers Make
Waiting Too Long
Program funds can run out. Prices and rates can also change. Start your lender search before you tour homes.
Skipping the Fine Print
Some assistance becomes due when you sell or refinance. Read the repayment terms. Ask your lender to explain each one.
Ignoring Long-Term Costs
Maintenance, insurance, and taxes add up over time. Plan extra payments later with our guide to paying off your home loan faster. Build an emergency fund before you close.
First-Time Buyer Program FAQs
Is Florida first-time buyer help a grant or a loan?
Many programs are repayable second mortgages. Some local programs offer grants. Ask your lender which options need repayment.
Can I use more than one program?
Sometimes. Rules differ by program, and Hometown Heroes may limit other Florida Housing programs. Confirm every combination with your lender.
How much do I need to save?
FHA loans start at 3.5 percent down. VA and USDA loans can require none. Assistance programs can cover part of the rest.
Should I talk to a lender before I tour homes?
Yes. A lender can confirm your budget and program options. You then shop with a firm price range. Sellers also take pre-approved offers more seriously.
Do Hometown Heroes funds run out?
Yes, they can. Florida Housing committed last year’s funds in six months. Check current availability before you plan around the program.